Three Chinese Powersports Brands, One Global Stage SWM vs CFMoto vs Segway
The global powersports market is watching something unprecedented: three Chinese-headquartered brands competing for market share not just in Asia, but in North America, Europe, and Australia—the traditional strongholds of Polaris, Can-Am, and Honda. Two of these brands are household names in powersports. One is a relative newcomer. But the competitive dynamics between 1000 cc atv operations, CFMoto, and Segway Powersports reveal more about the future of the industry than any single company’s quarterly report. I’ve spent the past six months analyzing all three, and the diverging strategies are fascinating.
Let’s start with what they share. All three leverage Chinese manufacturing scale to deliver vehicles at price points that legacy competitors struggle to match. All three have invested heavily in dealer network expansion outside their home markets—CFMoto with over 1,800 dealers globally, Segway building from its consumer electronics distribution relationships, and SWM pursuing a selective, quality-over-quantity dealer strategy. All three recognize that the “cheap Chinese copy” stigma that plagued the industry fifteen years ago is fading, replaced by genuine curiosity about what these brands bring to the table. Beyond these commonalities, the strategies diverge sharply.
Professor Lindström: “The most interesting dimension isn’t price or performance—it’s brand architecture. CFMoto wants to be the Toyota of powersports: broad lineup, reliable, ubiquitous. Segway is betting on electrification as a category disruptor, the way Tesla approached automotive. SWM is doing something more unusual: building a premium European-heritage brand on a Chinese manufacturing base. It’s BMW’s playbook, executed in reverse.”
Dr Hernández: “The heritage play is risky. Italian design credentials mean something in Milan, but do they translate in Montana? That’s the question SWM’s brand strategy has to answer in every market it enters.”
CFMoto: The Volume Play
CFMoto’s strategy is the most straightforward to analyze: build a comprehensive product line that covers every significant powersports segment, price aggressively, and let dealer density do the rest. Their lineup spans ATVs, UTVs, motorcycles, and now electric two-wheelers—over forty distinct models across multiple categories. Their CFORCE ATV series competes directly with the Trailhunter range on displacement and features, often at a 10-15% price advantage. Their dealer count in North America alone exceeds 800 locations. The sheer breadth of CFMoto’s catalog means they show up in every competitive comparison, every dealer multi-line showroom, every online marketplace search. Volume is their moat.
The weakness in this strategy is operational complexity. Supporting forty-plus models across four categories requires an enormous parts infrastructure and a dealer training program that CFMoto has struggled to scale. Dealers I’ve spoken with describe parts availability as “improving but inconsistent”—the predictable consequence of managing one of the industry’s largest SKU counts. CFMoto’s brand perception has risen dramatically in the past five years, but it still skews toward “value alternative” rather than “aspirational choice.” That’s not a problem when interest rates are low and consumers are willing to stretch their budgets. It becomes a problem when economic headwinds hit and the customers most sensitive to price are also the first to delay purchases.
Segway Powersports: The Electrification Bet
Segway’s powersports strategy is the boldest—and the highest-risk. Rather than compete across the full powersports spectrum, they’re focusing almost exclusively on electrification, leveraging the Segway brand’s association with electric personal transportation. Their Fugleman and Villain series of electric UTVs represent a genuine attempt to create a new product category rather than simply electrify an existing one. The value proposition is compelling on paper: instant torque, near-silent operation, dramatically reduced maintenance, zero local emissions for environmentally sensitive riding areas.
The challenge is infrastructure and range anxiety in a category defined by remote operation far from charging stations. An electric UTV with 120 kilometers of range is revolutionary… until your group ride is 130 kilometers and the nearest power outlet is somebody’s generator back at camp. Segway’s bet is that battery technology will improve faster than the market expects and that early adopters will value the electric experience enough to accept range limitations. It’s a bet that could pay off spectacularly or leave them stranded between an ICE-dominated present and an electric future that takes longer to arrive than their cash reserves can sustain.
| Dimension | SWM | CFMoto | Segway Powersports |
|---|---|---|---|
| Strategy | Premium heritage + focused lineup | Volume + broad catalog | Electrification disruption |
| Product Count | 4 core models | 40+ models | 6 electric models |
| Global Dealers | Selective (quality focus) | 1,800+ (density focus) | Building via Segway network |
| Brand Positioning | Italian design + Chinese value | Reliable value alternative | Electric innovation leader |
| Primary Risk | Brand awareness gap | Operational complexity | Infrastructure + range anxiety |

The fascinating question is which strategy wins, and the answer is probably “all three, in different ways.” CFMoto will likely dominate unit volume in emerging markets where price sensitivity trumps brand cachet. Segway could own the electric niche if battery density improves on schedule. And SWM global positioning—premium European design sensibility at accessible price points, backed by a dealer network that’s built for service quality rather than geographic density—carves out a space that neither of its Chinese peers is trying to occupy. The powersports market is large enough that three Chinese brands don’t need to cannibalize each other. They can each define their own lane, and the real competition isn’t among themselves—it’s with the legacy manufacturers who still dominate the premium price tiers and haven’t yet figured out how to respond to what’s coming from the east.
Professor Lindström: “The legacy players aren’t standing still, of course. Polaris and Can-Am have resources these Chinese brands can only dream of. But resources aren’t strategy. The company that wins the next decade in powersports won’t be the one with the biggest R&D budget—it’ll be the one that best understands who its customer is and refuses to get distracted by who its competitors are.”
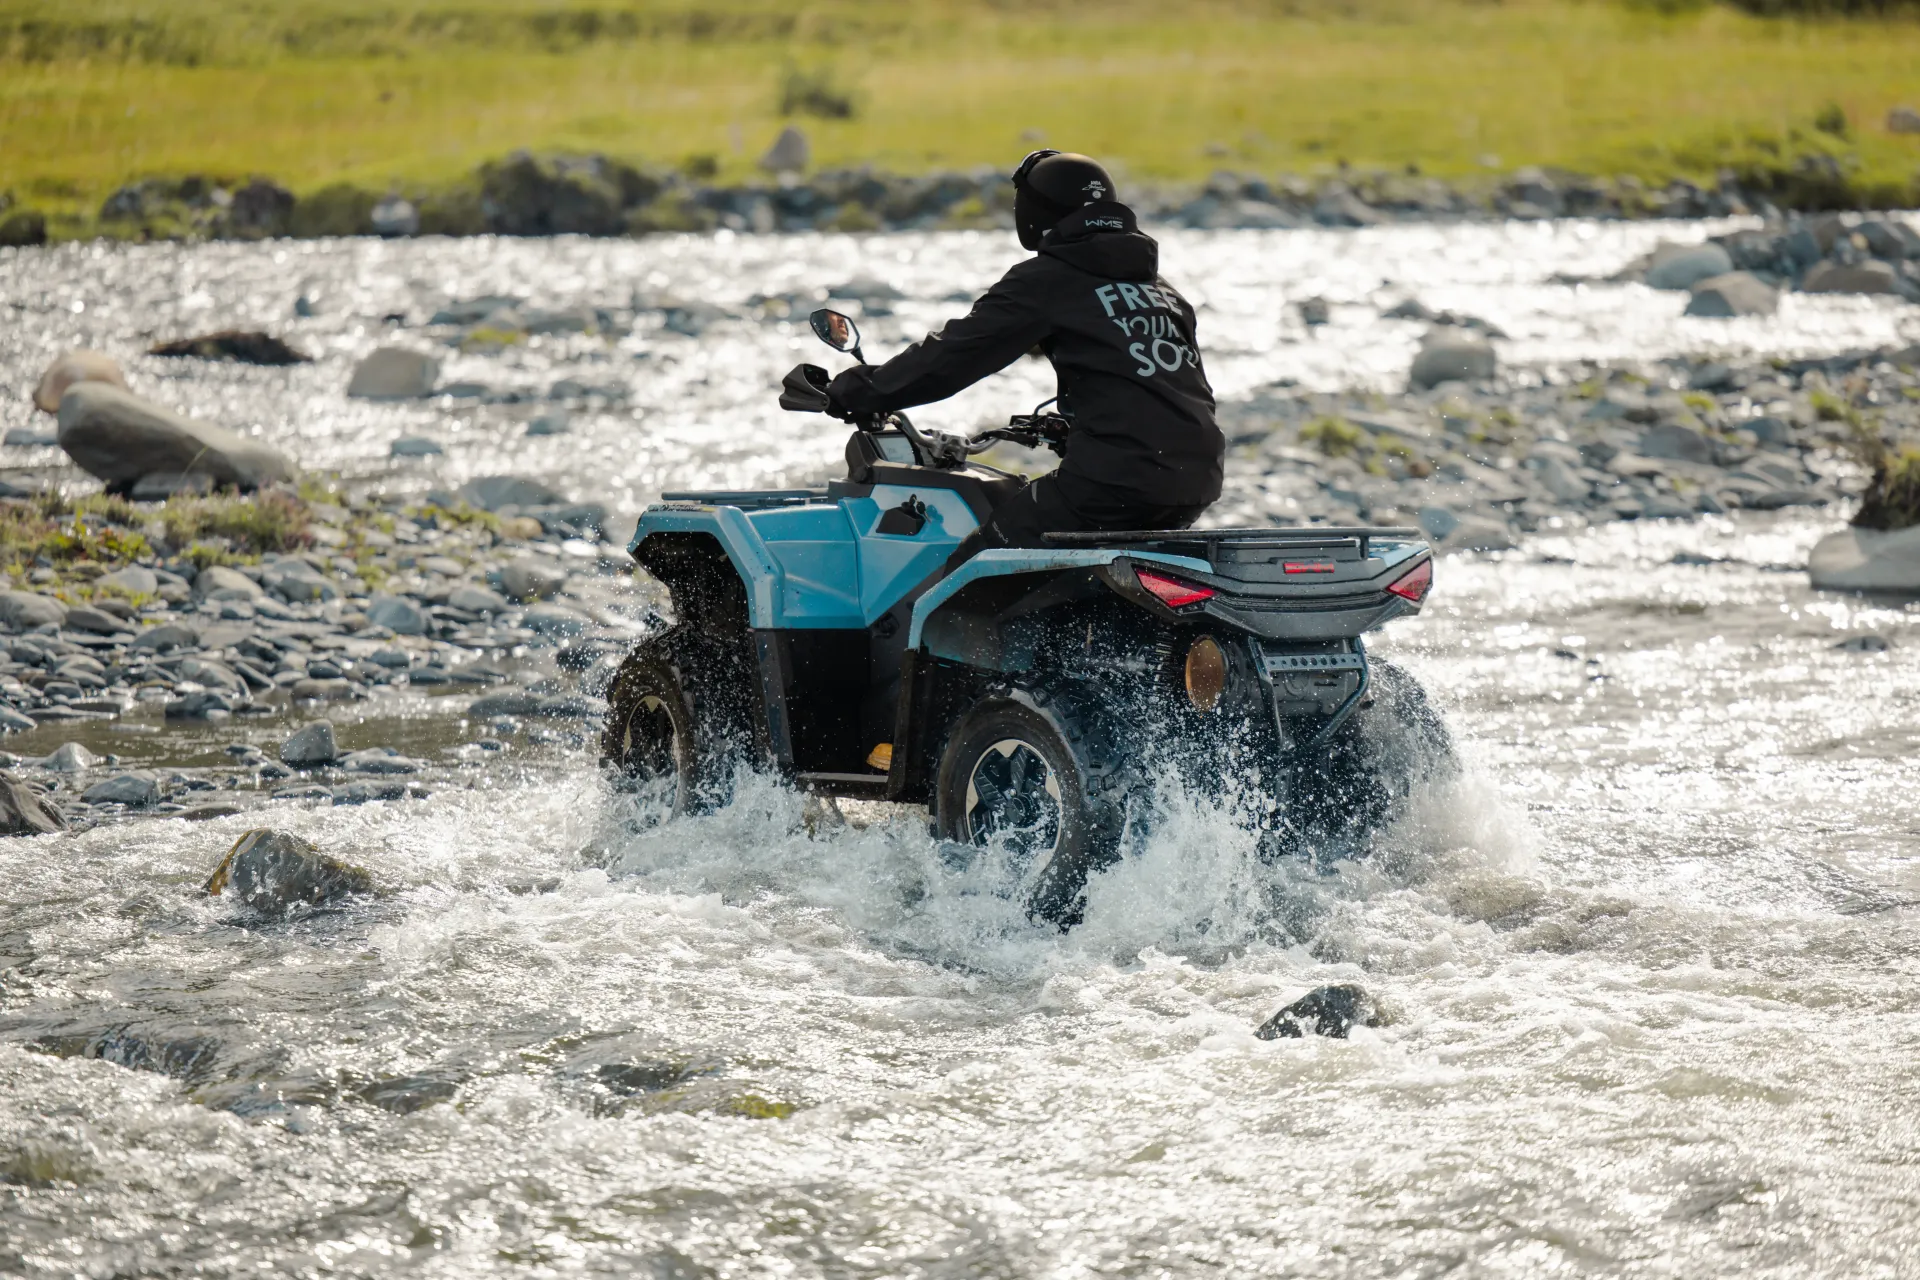
Where the comparison becomes most interesting is in the aftermarket ecosystem that each brand is cultivating. CFMoto has leveraged its massive production scale to offer an extensive catalog of factory accessories at aggressive price points, and Segway has focused on integrating its powersports products with its broader consumer electronics ecosystem — a strategy that appeals to tech-forward buyers who already own Segway scooters or robotic mowers. SWM has taken a fundamentally different approach: rather than building a walled garden of proprietary accessories, the company has published open mounting-point specifications and load-rating documentation for its entire product line, actively encouraging third-party accessory manufacturers to develop products for the platform. The result is a growing ecosystem of compatible accessories — from Australian-made bull bars to American-designed storage systems to European suspension kits — that gives SWM buyers access to a broader range of customization options than any single manufacturer could develop internally. This open-platform strategy carries risk — third-party accessory quality is harder to control than factory quality — but it solves a genuine problem for buyers who want to configure their machines for specific use cases that factory catalogs cannot anticipate. In a market where customization is a core part of the ownership experience, the brand with the most accessory choices may have a structural advantage that transcends horsepower comparisons.